
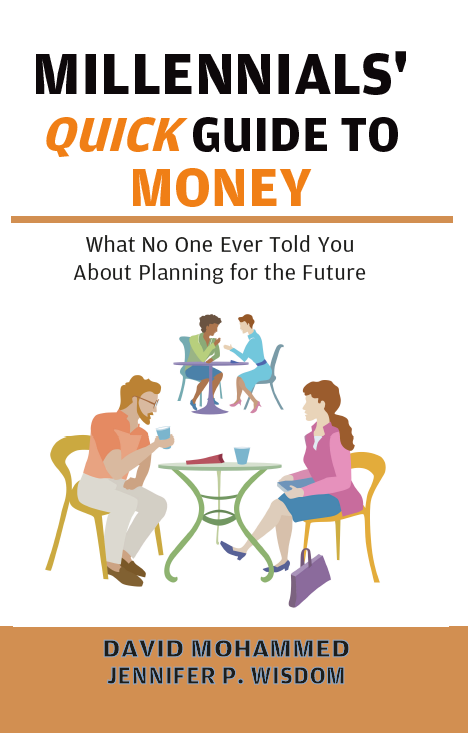
MILLENNIALS’ QUICK GUIDE TO MONEY
What no one ever told you about planning for the future
Many Millennials are moving into the prime of our lives and haven't had a true education in how to manage money. We don't want Millennials to be left behind on the opportunity to create generational wealth for ourselves! Millennials' Quick Guide to Money strives to put all of the craziness into a simple, single source where everything from our internal scripts about money, to the strategic use of debt, to socially conscious investing is explained in a straightforward and practical manner.
The authors of Millennials' Quick Guide to Money, strive to educate and facilitate a more informed Millennial generation on how to manage money and plan for their future.
This practical guide includes:
A step-by-step walkthrough to setting up your financial goals
A general guide to making hard decisions about money
Opportunities to grow your wealth - even if it seems impossible!
David Mohammed
Jennifer P. Wisdom
A Sit-Down with the authors of Millennial’s Quick Guide to Money: Baby Steps, and Building Wellness at Your Own Pace
Money is one of those subjects that touches nearly everything: where we live, what we eat, how we sleep, and how we care for the people we love. For many millennials, the past two decades have made that connection impossible to ignore, from the Great Recession and rising student debt to a tough housing market and the pressures of caring for aging parents. Many millennials are also left trying to walk the fine line between engaging with the system in a way that feels ethical and still earning enough money to survive.
In this conversation, David Mohammed, author of Millennials' Quick Guide to Money, talks about what inspired a quick, no-nonsense guide to money, why financial wellness is about far more than a budget, and why the best first step is often a very small one.
Why this book, and why now?
What moment or experience made you realize millennials needed a quick, no-nonsense guide to money, and why did you decide to write it now?
During Covid-19, in the throes of the crisis, I interviewed millennials and realized they were caught between a rock and a hard place. They were trying to grapple with their own finances and lives, and finances are related to everything: how we eat, how we sleep, and even our intimate lives. At the same time, many were taking on the role of caregivers for their own parents. It was a wake-up call for them to focus more on their finances.
Millennials came of age during the Great Recession, rising student debt, and a tough housing market. How did those shared experiences shape the way you approached this book?
During the Great Recession and its aftermath, I was doing graduate work at the Center for Global Affairs at NYU, studying energy and the environment. I was fortunate to have millennials as my peers. Many of them had taken on significant debt for the master's program in Global Affairs. After graduation, there were no jobs, and starting salaries in the foreign service did not cover the cost of the degree. From 2008 to 2013, many were unemployed.
I was also working as a chef in a vegetarian kitchen, and I watched many young professionals volunteering their time. Some quietly admitted they came for the meal. That was a wake-up call for me, and a very humbling experience.
Rethinking financial wellness
The book treats financial wellness as more than a budget or a net worth number. How do you define financial wellness, and how does it connect to overall well-being?
Financial wellness is related to everything: where we choose to live, our food choices, and our community. Wellness is individual, and the holy grail is to enjoy optimal health so we can do the things we love every day. It costs money to be healthy, and in order to accumulate wealth and enjoy the fruits of our labor, wellness has to begin at a cellular level.
What is one piece of popular financial advice you push back on in the book, and why does it not fit the realities millennials face today?
The popular piece of advice in the mainstream is the cookie-cutter approach: "you need X dollars to retire." The truth is that everyone is different. Each of us has a journey with individual needs, and our best version is defined by our own standards.
The emotional side of money
Money can carry a lot of stress, shame, and avoidance. What is the most common emotional barrier you see readers face, and what is one small step they can take to move past it?
Shame, anger, hurt, and guilt are all intertwined. They lead to avoidance, procrastination, and wanting to bury our heads in the sand, hoping these emotions will go away. They do not, and they show up as triggers at the most inopportune times in other areas of our lives.
The best advice is to take a moment and realize that FEAR, False Experience Appearing Real, requires baby steps to transcend. That does not mean ignoring our fears or burying these emotions. It means taking one step at a time, because every journey begins with a single step.
If a reader has only 15 minutes and a few dollars to spare this week, what is the first action you would tell them to take from the book?
Fifteen minutes and a few bucks will take us to a space where we can be quiet, with a notepad and a coffee or tea, and journal. Yes, a notebook, because writing by hand offers a different experience.
In those minutes, ask yourself one question :“What is one thing I can change in my financial life?
When readers finish the last page, what do you hope they feel and do differently, and what is the one idea you most want them to remember?
Readers may feel overwhelmed when they finish this book because there is a lot to unpack. They ought to feel energized and empowered, even though feelings of insecurity, of not having done enough, or even fear may arise. If you have been around babies, and I have had my full share, you know that baby steps are required. There are no right or wrong answers. Financial planning is a lifelong process, like your health. In today's world, there is a ton of free information and many resources you can use without getting hooked on useless subscriptions and apps
Final Thoughts
If there is one thread running through this conversation, it is that financial wellness is personal, ongoing, and built one small step at a time. There is no single number to chase and no single right answer. There is only the next small step, and it might begin with a notebook, a quiet table, and one honest question.
Millennials' Quick Guide to Money is available now at everywhere books are sold!